
History of EOG Resources
A 1999 separation from Enron: an unlikely origin that mattered
EOG Resources’ modern independent history dates to 1999, although the corporation itself was organized in 1985. On August 16, 1999, EOG and Enron completed a share exchange through which EOG transferred the subsidiary holding its India and China operations to Enron in exchange for 62.27 million EOG shares owned by Enron, which EOG then retired. Related share sales and exchangeable notes further reduced Enron’s interest, and Enron-affiliated directors resigned from EOG’s board. On August 30, the company changed its name from Enron Oil & Gas Company to EOG Resources, Inc. When Enron later collapsed into bankruptcy in 2001, EOG was already operating independently.
EOG’s plan was straightforward: concentrate on finding and producing oil, natural gas, and natural gas liquids. The 1999 separation left it as a focused exploration and production company rather than part of Enron’s trading and utilities conglomerate.
EOG was already a publicly traded company listed on the New York Stock Exchange under the ticker EOG before the 1999 separation, and its shares continued trading under that symbol afterward. At the time of independence, its principal executive offices were at 1200 Smith Street in Houston, Texas.
From corporate separation to independent E&P: the first decade
In its earliest independent years, EOG behaved like a traditional exploration and production company. The technical staff that moved into the independent firm brought exploration experience, existing acreage positions, and producing assets. The company then managed and developed that portfolio as a stand-alone business.
Rather than relying primarily on large acquisitions, EOG leaned heavily on developing its own acreage and on disciplined capital allocation. That approach supported organic production growth and positioned the company to capitalize on the technology shifts that would reshape onshore production in North America.
Adopting shale-era techniques: horizontal drilling, completions, and scale
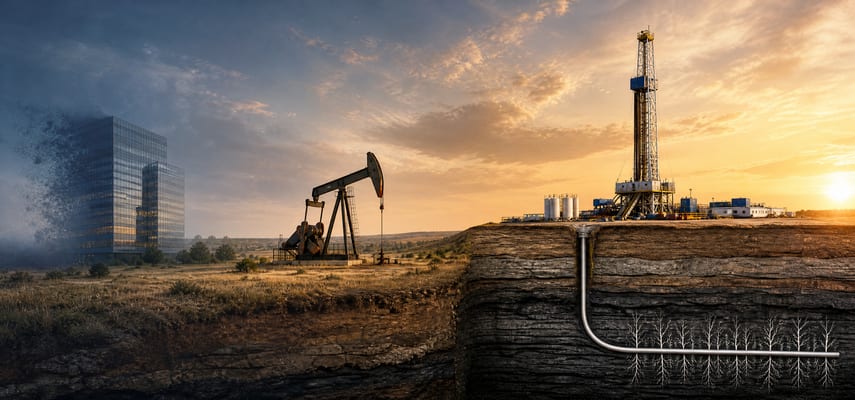
The biggest technical turning point for EOG, as for other independents, was the combination of horizontal drilling and slickwater hydraulic fracturing. These techniques unlocked resource potential in tight sands and shales that conventional vertical wells could not produce economically. EOG’s strategy was not merely to experiment with those tools but to apply them at commercial scale in liquids-rich plays.
Throughout the 2000s and into the 2010s, EOG directed investment into U.S. onshore basins that offered the best combination of geology and existing acreage. The company concentrated on plays where higher oil and condensate content made wells more profitable even when gas prices were weak. That emphasis on liquids became central to EOG’s growth strategy as the company shifted away from its earlier dependence on natural gas.
Applying these drilling and completion techniques at scale required changes to project planning and operations. EOG invested in seismic interpretation, completion design, and pad-drilling logistics. The payoff was higher initial production rates from new wells, reduced per-well costs, and a faster pace of development across contiguous acreage.
Geographic focus: the Permian and other high-value plays
EOG’s expansion in the shale era shows a clear pattern: concentrate capital where geology and existing position already favored growth. The Permian Basin — particularly its Midland and Delaware sub-basins — became a major focus because of stacked pay zones and large contiguous blocks. EOG also developed significant positions in other liquids-rich regions such as the Eagle Ford and Bakken at various points in its history.
Concentrating in these plays did two things. First, it boosted growth: wells in liquids-rich rock produced larger cash flows per well than most traditional gas projects. Second, it created operational leverage: contiguous acreage enabled longer-running drilling campaigns, shared infrastructure, and faster learning about completion recipes. In short, geographic focus turned geological advantage into financial advantage.
Major milestones and cycles: growth, crashes, and recalibration
EOG’s corporate life has been governed as much by commodity cycles as by technological progress. Several milestones and turning points help explain how the company evolved.
- Separation and independence (1999). The August share exchange and related transactions ended Enron’s control, led to the resignation of Enron-affiliated directors, and were followed by the name change to EOG Resources.
- Resource-play adoption and production growth (2005–2014). EOG expanded from the Barnett Shale into oil- and liquids-rich plays including the Bakken, Eagle Ford, and Permian Basin, with the liquids transition becoming especially visible from 2009 through 2014.
- Oil-price collapse and capital retrenchment (2014–2016). In response to lower crude prices, EOG reduced its planned 2015 capital expenditures by 40 percent from 2014 and planned about 45 percent fewer well completions. Its 2016 plan called for another 45 to 50 percent reduction in capital expenditures and concentrated activity on its highest-return inventory.
- COVID and oil-market shock (2020). EOG ultimately reduced its 2020 capital plan by 46 percent from the original plan, slowed drilling, shut in some production, and sought to preserve its financial position and dividend.
- Expanded shareholder-return framework (2021–2024). EOG doubled its regular dividend rate and paid two special dividends in 2021, committed in 2022 to return at least 60 percent of annual free cash flow, and raised that minimum commitment to 70 percent effective in 2024. It returned $5.3 billion to shareholders in 2024 through dividends and repurchases.
These milestones progressively raised the importance of return thresholds, free cash flow, balance-sheet strength, and shareholder distributions in EOG’s capital-allocation strategy.
Key milestones (dates)
Timeline
- August 16, 1999 — EOG and Enron completed the share exchange that established EOG’s independence.
- August 30, 1999 — Enron Oil & Gas Company changed its name to EOG Resources, Inc.
- 2005–2014 — EOG expanded its use of horizontal resource-play development, moving from the Barnett into the Bakken, Eagle Ford, and Permian Basin and increasing its emphasis on liquids.
- 2014–2016 — The oil-price collapse prompted major capital reductions, fewer well completions, and increased concentration on higher-return acreage.
- 2020 — EOG reduced its capital plan by 46 percent from the original plan in response to the pandemic and oil-market downturn.
- 2021–2024 — EOG expanded regular and special dividends, formalized minimum cash-return commitments, and added substantial share repurchases.
Leadership, culture, and the management test
EOG’s leadership choices reinforced its operational culture: the company valued technical competence, measured execution, and financial discipline. Management communications emphasized exploration, production efficiency, investment returns, and a conservative financial strategy.
That culture shaped two kinds of decisions. Operationally, leaders pushed efficiency through better seismic work, improved completion design, and rigorous post-drill analysis. Financially, managers emphasized balance-sheet strength and predictable capital programs. Those choices made EOG attractive to investors seeking exposure to oil and gas production without the volatility of trading-focused firms or the complexity of supermajors.
Leadership and financial approach
Leadership and culture
Management prioritized technical depth and execution. The emphasis on measurable goals and operational rigor helped the company turn technical skill into repeatable drilling and completion outcomes.
Financial approach
EOG’s financial approach moved toward disciplined capital allocation, balance-sheet strength, and explicit mechanisms for returning surplus cash to shareholders. This emphasis recurs across cycles: invest when returns are high and conserve capital when prices and prospective returns fall.
Acquisitions and the role of organic growth
Organic exploration and development have been central to EOG’s history, but the company has also completed major strategic transactions. On October 4, 2016, EOG completed its combination with Yates Petroleum and affiliated entities for total consideration of approximately $2.4 billion, adding assets in the Delaware Basin, Powder River Basin, Permian Basin Northwest Shelf, and other western basins. On August 1, 2025, EOG completed its $5.6 billion cash acquisition of Encino Acquisition Partners, including debt repayment, adding 675,000 core net acres in the Utica play.
These transactions qualify EOG’s historical preference for organic, drill-bit growth. Between its larger deals, the company frequently emphasized internal exploration, low-cost acreage additions, exchanges, and tactical bolt-on acquisitions that complemented existing operating areas.
Challenges and controversies: regulatory, environmental, and market pressures
Like every large oil and gas producer, EOG has had to manage regulatory scrutiny, environmental criticism, and safety oversight. Hydraulic fracturing and increased production in densely populated regions generated public concern about groundwater, methane emissions, and flaring. Regulators at state and federal levels tightened reporting requirements, and public-interest groups pressed for stricter controls on emissions and water use.
Market pressures also posed an ongoing challenge. Price volatility — including the prolonged low-price stretch after 2014 and the shock of 2020 — made capital planning difficult. Investors pressed for clearer commitments on dividends, buybacks, and return of capital. EOG responded with programs to prioritize cash returns and to articulate capital plans tied to commodity-price scenarios.
Those responses shifted EOG’s public profile from pure growth to disciplined producer, aligning the company with a cohort of independents that sought to reassure markets after an era of cyclical overreach across the industry.
Recent years: capital discipline, shareholder returns, and operational refinement (2020–2024)
The most consequential trend in EOG’s recent history was a persistent shift in capital allocation and shareholder engagement. After reducing its capital program during the 2020 oil-market shock, EOG maintained return-focused investment programs and expanded explicit mechanisms for returning surplus cash to shareholders through regular dividends, special dividends, and share repurchases.
This change reoriented EOG’s decision-making. Where earlier growth phases prioritized production volumes and acreage hold, the company increasingly framed projects in terms of per-dollar returns and free cash flow under conservative price assumptions. That discipline affected drilling cadence, the pace of leasehold development in the Permian and other plays, and the willingness to delay lower-return projects.
Operationally, recent years saw continuous improvement rather than singular breakthroughs. EOG refined completion designs, reduced well-cycle times, and improved drilling efficiency in dense multi-well pads. Those iterative gains lowered costs and helped wells reach higher early production rates, improving short-cycle cash returns and enabling meaningful returns to investors without ever-larger drilling budgets.
Environmental management and reporting also became more visible in the company’s public communications. EOG, like many peers, increased disclosure about methane emissions, flaring, and efforts to electrify pumps or reduce emissions intensity at well sites. These steps responded to investor and regulatory pressure and aimed to protect the economic value of assets that could face higher regulatory costs if emissions were unchecked.
Legacy and industry influence
EOG’s historical significance flows from two durable choices. First, the company chose to be a focused upstream operator rather than a diversified energy conglomerate. That focus allowed EOG to build technical depth and direct capital where it produced the highest returns. Second, EOG embraced and scaled the drilling and completion techniques that unlocked shale resources across North America. The company’s success in liquids-rich plays helped change expectations for what onshore U.S. production could deliver.
Some practices EOG helped normalize became industry standards: emphasis on completion design, pad drilling for efficiency, and a data-driven approach to optimizing well spacing and decline curves. Competitors and service companies adopted variants and pushed the state of the art further. EOG’s legacy is not a single invention but a demonstrated pathway from technical experimentation to commercial scale.
How EOG today differs from its origin
The EOG that exists now shares DNA with the firm that separated from Enron in 1999 but also reflects a shift in priorities. The independent company initially depended heavily on natural gas production; its more recent defining characteristics include a liquids-rich, multi-basin portfolio, higher investment-return thresholds, and a formal cash-return framework. Through cycles of boom and bust, EOG refined a playbook: invest where wells show high returns, cut back when prices and returns fall, and return cash to shareholders when financial conditions permit.
Technically, the company operates in a world where horizontal wells, multi-stage fracturing, and pad operations are standard. Financially, peer expectations emphasize conservatism: controlled budgets, realistic commodity-price assumptions, and steady cash distribution.
Conclusion: a focused producer that learned from crisis
EOG Resources’ independent history traces a clear arc. Separated from Enron through a 1999 share exchange and related transactions, it pursued a focused upstream strategy centered on finding and producing oil and gas. Technological change — horizontal drilling and hydraulic fracturing — created the main growth opportunity, and EOG leaned into the plays where that technology produced the best returns. Commodity cycles forced recurrent course corrections, and each downturn reinforced the company’s commitment to capital discipline.
Across its history EOG translated technical competence into a repeatable financial model: develop high-quality acreage with efficient wells, manage spending through cycles, selectively supplement the portfolio through acquisitions, and return surplus cash to owners. That trajectory — from Enron-controlled producer to a disciplined, independent multi-basin operator — is the defining story of EOG Resources.
References
See the timeline and in-article sections above for the major milestones and context.