

History of State Farm Insurance
A neighborly idea that became a national insurer
Quick facts
- Founded: 1922
- Founder: George Jacob (G.J.) Mecherle
- Headquarters: Bloomington, Illinois
- Structure: Mutual insurer with exclusive local agents
- Major legal event: State Farm v. Campbell (2003)
- Leadership transition: Ed Rust Jr. stepped down as CEO in September 2015; Michael L. Tipsord succeeded him and became chairman in June 2016
- Contemporary pressures: digital distribution and catastrophe risk (2010s–2020s)
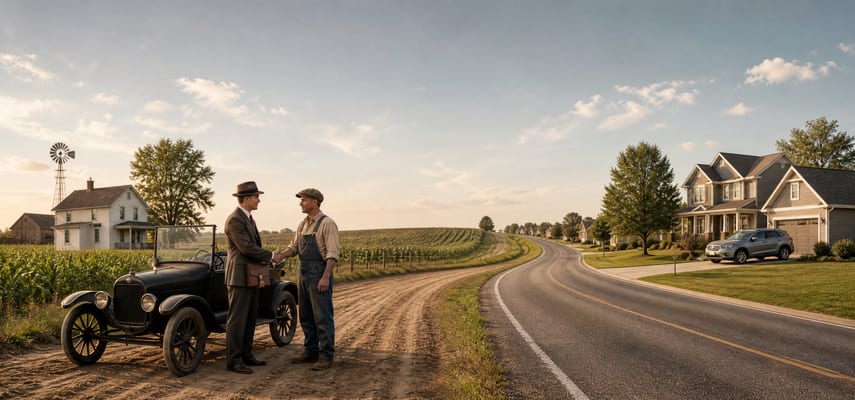
State Farm began with a simple, contrarian idea: ordinary farmers and rural drivers could be insured against automobiles at a fair price by a company owned by its policyholders. In 1922 George Jacob (G.J.) Mecherle, an onetime farmer and former insurance agent in central Illinois, set out to write automobile coverage tailored to rural motorists and sold through local agents he trusted to judge risk fairly. He named the business State Farm Mutual Automobile Insurance Company and founded it in Bloomington, Illinois. What started as an effort to offer fairer, risk-based auto insurance to rural drivers grew into a nationwide mutual insurance group whose practices—exclusive agents, mutual ownership, and emphasis on local underwriting—shaped American property–casualty insurance for much of the twentieth century.
Origins and founding: Bloomington, a mutual model
Mecherle incorporated State Farm in 1922 at a moment when the automobile was changing American life but insurance practices lagged behind. Rural drivers were often charged the same rates as city motorists even though their exposure patterns differed. Mecherle’s answer was a mutual insurer: policyholders would be the owners, reducing the pressure to generate shareholder returns.
He recruited agents from local communities and emphasized conservative underwriting, low operating costs, and steady premiums. State Farm built its distribution around local agents and mutual ownership, with policyholders as members of the company.
Early development: agents, claims, and organic growth
During its first decade, State Farm expanded rapidly, operating in 29 states. It built an exclusive-agent model in which independent-contractor agents marketed State Farm-branded products from local offices. That model aligned commissions and incentives toward long-term customer relationships rather than one-off sales.
Claims handling became a practical discipline for the young company. State Farm emphasized quick local investigation and conservative reserves—practices that reinforced policyholder confidence. During periods of economic stress, most notably the Great Depression, the mutual structure and tight cost controls helped State Farm remain solvent while competitors faltered.
Expansion and product diversification: beyond the Model T
After establishing a firm foothold in auto insurance, State Farm launched its life company in 1929, formed State Farm Fire Company in 1935, and introduced a multi-peril homeowners policy in 1956. State Farm began banking operations in March 1999; in 2020 it announced an exit from banking operations and an alliance under which U.S. Bank assumed its deposit and credit-card accounts. The firm used its exclusive-agent distribution network to offer complementary products and deepen customer relationships.
Geographic expansion was methodical—state by state—rather than driven solely by rapid national advertising. That conservative, agent-driven growth produced a large, diversified portfolio of insurance businesses by the second half of the twentieth century.
Branding and the “good neighbor” identity
As State Farm moved from a regional carrier to a national brand, it invested in advertising that reflected its practical, local image. For decades the company leaned on the idea of dependable local agents and a reassuring, neighborly voice rather than avant-garde marketing. The familiar slogan linking the company to everyday reliability became a core part of its public identity and reinforced the agent-centered model: the message emphasized personal service and reliability over technological novelty.
Major milestones: scale, diversification, and litigation
Certain events punctuated State Farm’s steady expansion and forced the company to adapt in ways that reshaped risk management and corporate practice.
- Scale and organizational complexity. Over the late twentieth century State Farm evolved from a single-company mutual into a group of legally distinct entities—property–casualty companies, life insurers, and financial-services affiliates—operating under the State Farm brand. The structure preserved mutual ownership at the top level while allowing separate underwriting and regulatory treatment for different lines of business.
- Legal turning point—State Farm Mutual Automobile Insurance Co. v. Campbell (2003), 538 U.S. 408. The U.S. Supreme Court held that a $145 million punitive-damages award accompanying $1 million in compensatory damages violated due process. The Court said that, in practice, few punitive awards exceeding a single-digit ratio to compensatory damages will satisfy due process, while stressing that there is no rigid numerical benchmark.
These milestones pushed State Farm beyond local underwriting: legal constraints, product diversification, and regulatory complexity required more centralized risk management and greater investment in actuarial modeling, catastrophe planning, and reinsurance.
Leadership and organizational change: continuity and modern management
State Farm’s evolution was shaped as much by management continuity as by disruption. Leaders with long tenures reinforced the mutual, conservative ethos and the exclusive-agent distribution model. Senior executives tended to rise from within the company and emphasize underwriting discipline, loss-reserving, and agent relationships, producing stability across decades.
Edward “Ed” Rust Jr. stepped down as chief executive in September 2015, when Michael L. Tipsord succeeded him as CEO. Rust remained chairman until June 13, 2016, when the State Farm Mutual board elected Tipsord chairman. The transition signaled a new generation of management while retaining the firm’s mutual philosophy. The new leadership faced contemporary pressures such as digital distribution and climate-driven catastrophe risk while continuing to emphasize agent relationships and conservative underwriting.
Acquisitions, ownership, and the limits of external growth
Unlike some insurers that accelerated growth through large acquisitions or public equity offerings, State Farm’s expansion was predominantly organic. The mutual form limited the company’s incentive to seek outside capital markets; policyholders were the effective owners. As a result, State Farm did not convert to a publicly traded company and avoided the pressures that can push firms toward short-term profit-seeking.
Because the company grew from local underwriting and agent networks, acquisitions played a smaller role compared with recruitment of agents, geographic licensing, and internal product development. This discipline reduced integration risk but also limited rapid entry into new lines where external expertise might have accelerated development.
Challenges and controversies: claims, catastrophes, and regulatory scrutiny
Operating a massive insurance franchise has exposed State Farm to recurring challenges. Large natural catastrophes—hurricanes, tornadoes, and wildfires—test any insurer with a broad footprint, and State Farm has not been immune. High-loss years forced the company to adjust rates and underwriting standards in exposed markets, often drawing public scrutiny when homeowners faced non-renewal or higher premiums.
State Farm has also faced individual bad-faith suits and regulatory inquiries related to claims handling. The 2003 Supreme Court case is the most prominent legal event with national implications, but a steady stream of state-level disputes over claims after disasters has shaped the company’s practices. Regulatory examinations have at times required corrective action related to claims handling.
Digitalization and product innovation in the 21st century
Entering the 2000s and accelerating in the 2010s, State Farm confronted technological change that threatened its traditional distribution model. Customers increasingly researched policies online, compared prices on aggregator sites, and expected fast digital claims service. State Farm’s response combined digital investment with reinforcement of its core agent network.
The company rolled out telematics-based programs that let drivers earn discounts for safe behavior; it expanded mobile claims apps and automated features to speed repair and settlement workflows; and it invested in data and analytics to refine underwriting and catastrophe modeling. These moves preserved the agent relationship while meeting customer expectations for convenience and personalized pricing.
Recent developments and State Farm’s position
Through the 2010s and into the early 2020s State Farm remained organized as a mutual group headquartered in Bloomington, Illinois, operating multiple licensed insurance companies under the State Farm brand. Its principal offerings continue to be automobile and homeowners/property–casualty insurance, supplemented by life insurance and financial services offered through affiliated entities and third-party alliances. Revenue and profit figures fluctuate with underwriting cycles, investment returns, and catastrophe losses; the mutual form keeps capital management anchored to policyholder interests rather than shareholder demands.
Recent years have tightened focus on a few durable problems for State Farm and its peers: catastrophe exposure, digital distribution, and regulatory and litigation pressures. Increasing frequency and severity of weather events have pushed insurers to reassess pricing and geographic exposure. Direct online sellers and insurtech startups press traditional agent sales, and state-level rate approvals and litigation over claims remain operational realities.
Legacy and significance: how a farmer’s experiment changed insurance
State Farm’s historical significance rests on several contributions to American insurance:
- Agent-centered distribution. The exclusive-agent model reduced turnover and aligned agents’ incentives with long-term customer retention.
- Mutual ownership model. Operating as a mutual insurer shaped strategic choices; without public shareholders, the company could prioritize reserve strength and conservative underwriting.
- Claims practice and litigation impact. State Farm’s litigation history includes the 2003 Campbell decision, a major U.S. Supreme Court ruling on constitutional limits for punitive damages.
- Practical brand and marketing. The steady, neighborly brand voice showed the value of consistent messaging tied to a local distribution model.
Not every idea endured. The conservative, agent-first approach delayed some digital pivots and left room for direct sellers and insurtech firms to capture digitally native customers. Still, the combination of local underwriting judgment, policyholder ownership, and scale made State Farm a template for a large, diversified mutual insurer.
Conclusion: from a farmer’s practical fix to a modern insurance franchise
State Farm’s history is a long sequence of practical adjustments. George Mecherle’s 1922 experiment answered a narrow market problem—rural motorists paying unfair urban rates—with a mutual insurer and a disciplined agent network. That structural choice shaped nearly everything that followed: how the company scaled, priced risk, and weathered legal and natural-catastrophe shocks.
Major turning points—the slow diversification beyond auto, the increasing complexity of a national insurance group, the 2003 Supreme Court decision that provided due-process guidance on punitive damages, and the digital and catastrophe challenges of the 2010s and 2020s—forced adaptation. Yet the durable core remained: policyholders as owners and local agents as the primary interface. In that sense State Farm is a study in institutional continuity, showing how conservative choices can produce a large, resilient company even as climate, technology, and legal pressures compel ongoing change.