










History of Baker Hughes
Introduction: Two century-old names, one modern oilfield-services company
Through mergers, regulatory battles and strategic pivots, Baker Hughes evolved from separate drill-bit and well-service businesses into a diversified energy-technology and services firm.
The story of Baker Hughes begins with a contradiction: the company that today bills itself as an equipment, services and digital supplier to the energy industry is the product of two very different early 20th-century inventions. One founder built a business on a better drill bit; the other built a business on the practical hard work of servicing wells.
Their marriage created a firm that has tried repeatedly to bridge manufacturing, field services and data — and that has been pulled between the demands of national regulators, global oil markets and the push into lower-emission energy technologies.
Baker Hughes is a Houston-based provider of oilfield services, equipment and energy-technology solutions. Its current legal name is Baker Hughes Company, and its structure owes much to a cascade of consolidations, attempted mergers and the 2017 combination of Baker Hughes with General Electric’s oil-and-gas business. That history matters because Baker Hughes has helped define how oil producers drill, monitor and manage wells while also illustrating how an oilfield-services company adapts when its core market shifts and regulators raise the bar on consolidation.
Origins and founding: Hughes Tool and the Baker name
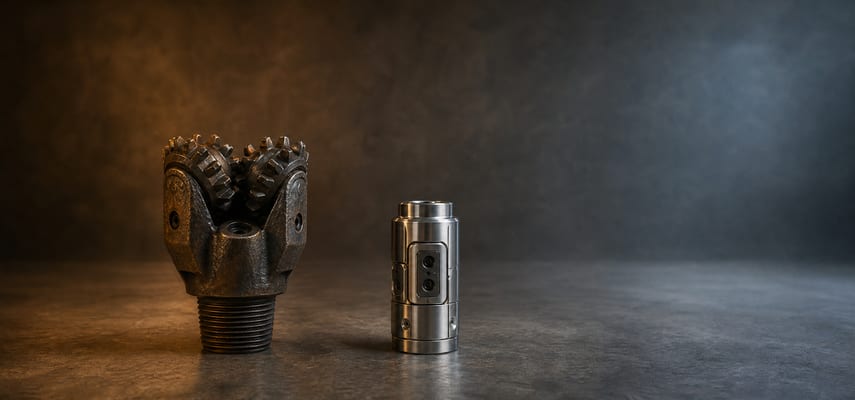
Baker Hughes traces its roots to two distinct early businesses. In 1908 Howard R. Hughes Sr. and Walter Sharp built and successfully tested a two-cone roller bit designed for harder, deeper formations. Hughes received U.S. patents for the drill design on August 10, 1909, and the partners formed the Sharp-Hughes Tool Company in Houston that year. After Sharp’s death and Hughes’s acquisition of his partner’s interest, the business was renamed Hughes Tool Company in 1915.
The Baker side of the story began in 1907, when Reuben C. Baker patented a cementing casing shoe that helped drillers run and cement casing in oil wells. The Baker Casing Shoe Company was established in 1913 and later became Baker Oil Tools, building a broader business in completion, cementing and other downhole equipment.
Both lines of business — tools and hands-on well services — were central to the industrialization of oil production in Texas and beyond.
Early development: tools, services and the growth of an industrial ecosystem
During the 20th century, Hughes Tool and Baker-run businesses followed complementary but different trajectories. Hughes Tool focused on manufacturing the drill-bit technology that made it a global supplier to drilling contractors. The company was periodically reorganized around intellectual property and manufacturing capability; its prominence made the Hughes brand widely recognized in the drill-bit and downhole-tools market.
Baker’s growth was more operational. The firm expanded its on-site crews, developed casing and cementing techniques and built a business model based on recurring field contracts. As oil production moved offshore and into deeper, more complex reservoirs, Baker companies invested in personnel, specialized equipment and logistics.
That investment turned well services into a business with significant operational scale and recurring revenue — but also one that was labor- and capital-intensive and sensitive to oil prices. These complementary strengths — Hughes’s equipment and Baker’s field operations — set the stage for the late-20th-century consolidation that fused product manufacturing with service delivery under one corporate roof.
The 1987 merger: forming Baker Hughes and why it mattered
On April 3, 1987, Baker International Corporation and Hughes Tool Company completed a combination through a series of stock transactions. Both companies became wholly owned subsidiaries of a newly formed Delaware corporation named Baker Hughes Incorporated.
First, it reflected an industry trend toward vertical integration: oil producers preferred vendors that could supply both equipment and the crews to install and maintain it. By housing both capabilities, Baker Hughes could offer integrated solutions — drilling tools, completion equipment and the personnel to run a job — which simplified contracting for customers and expanded the company’s share of the value on each well.
Second, the merger created a larger firm with greater geographic reach and product scope, enabling investment in research and development and entry into offshore, international and reservoir-management services. The new Baker Hughes combined manufacturing scale with operational know‑how — a combination that shaped its opportunities and constraints in the decades that followed.
Expansion and diversification in the late 20th and early 21st centuries
After the merger, Baker Hughes pursued growth through geographic expansion, new product lines and periodic acquisitions. The company built capabilities in directional drilling, measurement-while-drilling technology, logging tools and reservoir surveillance.
- Directional drilling
- Measurement-while-drilling technology
- Logging tools
- Reservoir surveillance
The era was shaped by two broad trends. The first was technological: drilling and completion technology grew more complex, and operators demanded tools that could reach longer horizontal laterals, place completion equipment precisely and monitor downhole conditions. Baker Hughes invested in technologies and engineering expertise to meet those needs.
The second trend was cyclicality. Service revenues expanded when oil prices were high and contracted sharply during price downturns. That volatility pushed Baker Hughes and its peers to seek steadier revenue streams through long-term service agreements, aftermarket parts and technology offerings that could be sold outside boom cycles.
The Halliburton takeover attempt and regulatory rebuff (2014–2016)
On November 17, 2014, Halliburton and Baker Hughes announced a proposed acquisition under a merger agreement dated November 16. The proposed combination drew immediate attention because it would have united two of the three largest globally integrated oilfield-services companies and combined major competitors in areas including drilling fluids, cementing, directional drilling and other well-construction products and services.
On April 6, 2016, the U.S. Department of Justice filed a civil antitrust lawsuit to block the transaction. The DOJ alleged that it would eliminate significant head-to-head competition, threaten higher prices and reduce innovation in 23 U.S. product and service markets. Halliburton and Baker Hughes entered into a termination agreement effective April 30, 2016, and publicly announced the termination on May 1.
The failed deal exposed how concentrated certain oilfield-service markets had become after decades of consolidation. It also left Baker Hughes independent but highlighted its vulnerability to industry consolidation pressures: combination among the large suppliers could quickly reconfigure pricing and the pace of technology adoption in the field.
The GE tie-up and the BHGE era (2016–2019)
On October 31, 2016, General Electric and Baker Hughes announced an agreement to combine Baker Hughes with GE’s oil-and-gas business. The transaction closed on July 3, 2017, creating Baker Hughes, a GE company, commonly abbreviated BHGE. Its Class A shares began trading on the New York Stock Exchange under the symbol BHGE on July 5. Immediately after closing, GE held approximately 62.5% of the combined company’s economic interest, while legacy Baker Hughes shareholders held approximately 37.5%.
The combination was pitched as complementary. GE had strengths in turbomachinery, subsea processing equipment and industrial digital systems; Baker Hughes brought field services, drilling equipment and a global client base. The idea was to assemble an end-to-end supplier that included surface and downhole equipment, rotating machinery and analytics.
The BHGE marriage also reflected broader strategic currents: GE sought to reshape its portfolio and Baker Hughes gained access to industrial-scale manufacturing, capital and digital tools. The transaction created governance and integration challenges — cultural differences and structural adjustments — and did not eliminate the sector’s exposure to oil-price cycles or regulatory scrutiny.
Separation from GE control and return to the Baker Hughes name (2018–2019)
In June 2018, GE announced its intention to pursue an orderly separation from Baker Hughes. A November 2018 secondary offering and related share repurchase reduced GE’s interest from approximately 62.5% to approximately 50.4%. A further offering and repurchase completed on September 16, 2019, reduced GE’s ownership to approximately 36.8%, causing GE to cease being Baker Hughes’s controlling shareholder.
On October 17, 2019, the company changed its corporate name from Baker Hughes, a GE company to Baker Hughes Company. On October 18, its Class A shares began trading on the New York Stock Exchange under the new symbol BKR. This was a corporate name and ticker change rather than a new public listing.
Leadership and organizational shifts that shaped direction
The firm’s evolution has been steered by leaders who had to balance service operations, equipment manufacturing and, later, broader energy-technology ambitions. Lorenzo Simonelli became president and CEO of GE Oil & Gas on October 1, 2013. He became president and CEO of the combined Baker Hughes entity when the GE transaction closed on July 3, 2017, and was elected chairman on October 2, 2017. He remained chairman, president and CEO after GE ceased to be the controlling shareholder in 2019 and continued in those positions as of Baker Hughes’s February 2026 annual filing.
Under his leadership Baker Hughes pushed to combine traditional oilfield offerings with digital monitoring, turbomachinery and lower-carbon technologies. That shift reoriented investment toward products and services that operators increasingly demanded — efficiency, reliability and emissions reduction — while retaining the company’s service and equipment roots.
Challenges and controversies: cyclicality, regulation and the 2020 market shock
Baker Hughes’s history includes recurring operational and regulatory pressures. The failed Halliburton deal underscored antitrust risks for large-scale consolidation. The BHGE integration highlighted the difficulty of merging different industrial cultures and the risks created when a controlling shareholder changes strategic direction.
In 2020 the company confronted the simultaneous shock of the COVID-19 pandemic and a deep oil-price rout, which sharply reduced drilling activity and put pressure on service revenues and margins. Like its peers, Baker Hughes responded with cost reductions, portfolio prioritization and a renewed focus on stable, higher-margin business such as service contracts, engineered equipment and aftermarket parts.
The crisis also accelerated conversations about diversification into lower-carbon technology: customers facing emissions targets wanted options to decarbonize operations, opening an adjacent market for Baker Hughes while leaving revenue volatility tied to oilfield activity intact.
Recent development and current position (2019–mid‑2020s)
Since GE ceased to be its controlling shareholder in 2019, Baker Hughes has articulated a dual identity: it remains a major supplier of oilfield services and equipment while expanding into energy-technology markets tied to decarbonization and electrification.
Its offerings span multiple product and service areas:
- Drilling and completion tools
- Turbomachinery for gas processing and power generation
- Subsea systems
- Digital monitoring and analytics for rotating equipment and wells
The pivot toward lower-carbon technologies has concrete expressions. Baker Hughes’s 2025 Form 10-K identifies CCUS, hydrogen, clean power, geothermal and emissions abatement as parts of its strategy. In September 2024 it launched CarbonEdge, a CCUS monitoring and reporting platform, with Wabash Valley Resources as its launch customer. In March 2024 it said bp was using its flare.IQ technology at 65 flares across seven regions to quantify methane emissions and support earlier interventions. In October 2024 Dubai Petroleum ordered 10 Integrated Compressor Line units for the Margham gas-storage facility; the ICL is an electric motor-driven compressor designed to avoid operational seal leakage. Baker Hughes’s hydrogen work has included a 2022 field trial with Snam in Italy that used a 10% hydrogen blend at a gas-compression station and involved its NovaLT12 and PGT25 turbines. These activities diversify the portfolio, but Baker Hughes still serves customers whose near-term needs center on oil and gas production.
Operationally, the company has organized itself around product lines that combine hardware and software. Digital products — remote-monitoring platforms, predictive-maintenance analytics and software for real-time drilling optimization — are sold alongside equipment and field crews, leveraging Baker Hughes’s historical knowledge of how tools behave in the well and the ability to service them in the field.
Financially and structurally, the post-BHGE Baker Hughes remains publicly traded and headquartered in Houston. Management has emphasized cost discipline, a focus on high-margin aftermarket services and growth in energy-transition markets. Electrification of turbines, hydrogen infrastructure and carbon-capture projects require different sales cycles and partnerships than drilling crews do; the company’s progress can be measured by how effectively it converts customer relationships into opportunities for low-carbon solutions without sacrificing its core service business.
Legacy and significance: what Baker Hughes changed
Baker Hughes’s historical significance rests on a handful of concrete contributions and some durable lessons.
- Integrated tools and services. The 1987 merger that created Baker Hughes exemplified the industrial logic of offering both equipment and the crews to deploy it. That integration shaped procurement practices among oil producers and set expectations for bundled service contracts.
- Drilling technology and remote monitoring. The company’s ancestors — and the combined Baker Hughes — advanced roller-cone technology, directional drilling tools and later measurement-while-drilling and logging systems. Those technologies changed where and how wells could be drilled, enabling longer laterals and more complex completions.
- Aftermarket and engineered solutions. Baker Hughes helped expand the notion that equipment sales could be a gateway to recurring aftermarket business: parts, surveillance and long-term maintenance agreements that smoothed revenue volatility.
- A test case for industry consolidation and regulatory limits. The failed Halliburton bid showed the limits of combining major service providers and informed how future industry consolidation would be judged by regulators both in the U.S. and abroad.
- Transitioning a legacy supplier. In the 2020s Baker Hughes became a visible example of an oilfield-services firm attempting to move up the value chain into decarbonization technologies and digital services — a necessary shift if its long-term market is to include both hydrocarbons and lower-carbon energy systems.
Conclusion: from drill bits to decarbonization, a company shaped by markets and regulators
Baker Hughes began as two specialized players in the early oil age: one manufacturing a better drill bit, the other providing the labor and know‑how to run wells. Their combination produced a firm that could offer integrated equipment-and-service packages, a model customers adopted widely.
Major milestones — the 1987 merger, the aborted Halliburton deal, the tie-up with GE and the subsequent separation from GE control and 2019 name change — reveal recurring tensions: between scale and regulatory limits, between manufacturing and field operations, and between dependence on oil-price cycles and the desire for steadier, technology-driven revenue.
Today Baker Hughes is both deeply rooted in the practical work of drilling and maintenance and increasingly oriented toward the software, turbomachinery and low‑carbon technologies that customers now demand. How well it converts long-standing customer relationships and engineering expertise into leadership in emissions reduction and the energy transition will define the next chapter.












