

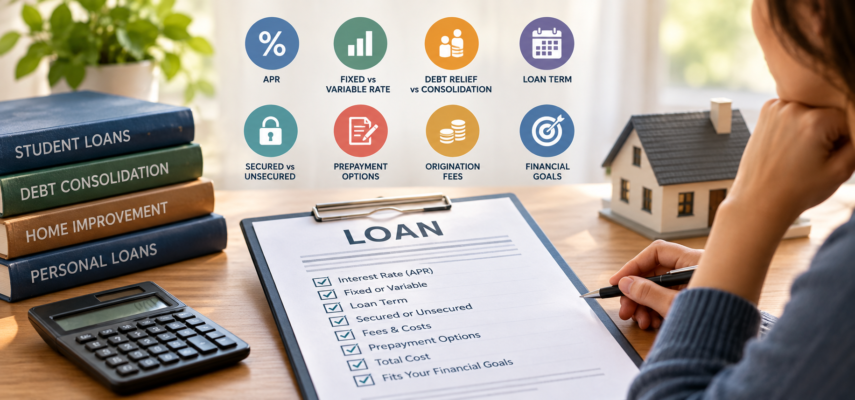
The choice between loan types, whether for student borrowing, debt consolidation, home improvement, or any other purpose, determines the total cost and risk of the borrowing. These eight considerations apply across loan types and help borrowers make more informed decisions before taking on new debt.
1. The Annual Percentage Rate Is the Most Accurate Cost Comparison
The nominal interest rate and the effective interest rate can differ significantly depending on compounding frequency and fees. The APR incorporates both the interest rate and any origination or other fees into a single annualized figure, making it the more accurate cost comparison across loans with different fee structures. Comparing APRs rather than stated interest rates gives you the closest thing to an apples-to-apples cost comparison between different loan products.
2. Fixed vs Variable Rate Affects Payment Predictability
Fixed rates provide payment certainty at a potentially higher starting point. Variable rates typically start lower but expose the borrower to payment increases if benchmark rates rise during the loan term. The choice depends on the expected rate environment, the borrower’s risk tolerance, and the loan term. For longer-term loans, the rate risk of a variable product carries more weight than for short-term borrowing where the exposure period is limited.
3. Which Is Better: Debt Relief or Consolidation for Managing Multiple Loans?
Freedom Debt Relief’s subsidized vs unsubsidized loans resource addresses how loan type affects management strategy, noting that the appropriate approach depends on the borrower’s financial situation. Consolidation works best when the borrower can qualify for better terms and manage the payment comfortably. Debt relief is more appropriate when the total debt load has become unmanageable regardless of the rate or structure.
4. The Loan Term Affects Total Interest Paid
A longer loan term reduces the monthly payment but increases the total interest paid over the life of the loan. The optimal term depends on the borrower’s cash flow needs and their capacity to make larger payments for a shorter period. Choosing the longest available term to minimize the monthly payment without considering the total cost produces the highest-cost version of any loan.
5. Secured vs Unsecured Changes the Risk Profile
Secured loans that use an asset as collateral offer lower rates but put the asset at risk if the loan is not repaid. Unsecured loans carry higher rates but do not create collateral risk. The appropriateness of each depends on the loan purpose and the borrower’s risk tolerance. Securing a discretionary purchase against the home is a different risk decision than securing a home improvement that adds value to the same home.
6. Prepayment Options Affect Long-Term Flexibility
Loans with prepayment penalties limit the borrower’s ability to pay off the debt early without incurring additional costs. Borrowers who anticipate the possibility of early payoff through a bonus, an inheritance, or aggressive additional payments should confirm the prepayment terms before accepting any loan to avoid a cost that offsets the benefit of early payoff.
7. Origination Fees Reduce the Net Proceeds
Origination fees that are deducted from the loan disbursement reduce the net amount received below the stated loan amount. A $10,000 loan with a five percent origination fee provides $9,500 in net proceeds while requiring repayment of $10,000 plus interest. This means the borrower needs to request a larger loan than they actually need to receive the target amount, which increases the total interest paid.
8. The Relationship Between Loan Terms and Financial Goals
The best loan is the one that most efficiently achieves the specific financial goal at the lowest total cost with an acceptable risk profile. A short-term consolidation loan that eliminates high-interest credit card debt quickly is different from a long-term home equity loan that funds a renovation, and the evaluation criteria should reflect what the loan is actually being used for rather than treating all loans as interchangeable.