

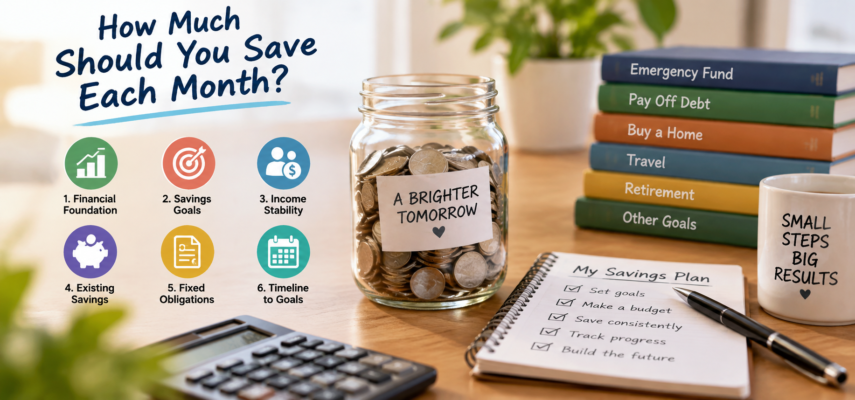
The question of how much to save each month does not have a universal answer. The number that is right for you depends on a combination of where you are financially, where you want to be, and what resources you have available to get there.
1. Your Current Financial Foundation
Before targeting a specific savings rate, the state of your existing financial foundation determines what the savings priority should be. If you have high-interest debt, aggressive debt paydown may produce better financial outcomes than maximizing savings.
If you have no emergency fund, building one takes priority over other savings goals because the absence of a cash buffer means any unexpected expense either disrupts other financial plans or creates additional debt.
2. What Should Be My Goal for Saving Money?
The right savings goal depends on what you are saving for and when you need it. SoFi’s how much to save per month calculator works backward from your target: enter the amount you want to save, the date by which you want to reach it, and the interest rate you expect to earn, and it tells you the monthly contribution required to hit the goal.
This approach is more useful than starting with a fixed savings percentage because it connects the savings target to a specific outcome rather than an abstract benchmark.
3. Your Income Stability
A stable salaried income and a variable freelance income require different approaches to monthly savings targets. With variable income, a percentage-based target that scales with the actual monthly income is more realistic than a fixed dollar amount that may be difficult to meet in lower-income months.
4. Your Existing Savings and Progress Toward Goals
The right monthly savings target is not the same throughout a financial journey. Benchmarking your current position against your goals, rather than against general guidelines, tells you whether the current savings rate is on track or whether it needs to increase.
5. Your Fixed Monthly Obligations
The amount available to save each month is constrained by what must be spent first. A budget that allocates savings before discretionary spending, treating the savings transfer as a fixed obligation, is more reliable than a plan that saves whatever happens to be remaining.
6. Your Timeline to Each Goal
The same total savings target requires very different monthly contributions depending on the timeline. Longer timelines produce more flexibility in monthly contributions and more total interest earned. Understanding the tradeoff between timeline and monthly contribution helps you prioritize which goals to fund aggressively.