










History of DXC Technology
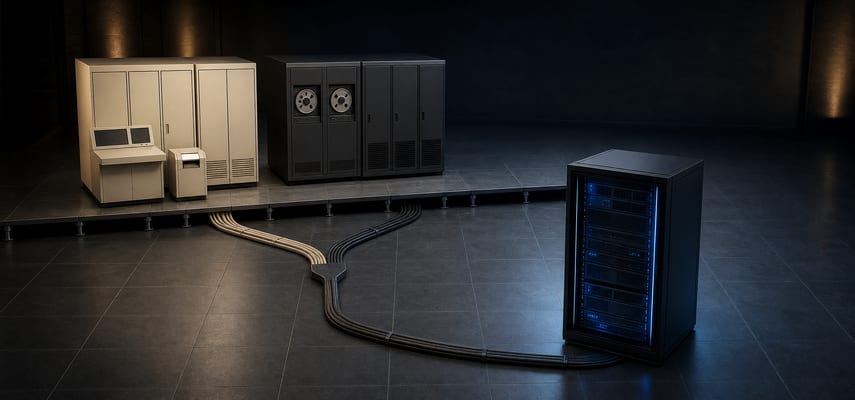
When DXC Technology arrived on the corporate stage in April 2017, it did so not as a startup with a bright new product but as a patchwork colossus: two venerable IT-services lineages folded together in a bid to remain relevant as the industry around them remade itself. That merger reflected decades of enterprise computing — the outsourcing boom of the 1990s, the rise of global delivery in the 2000s, and the cloud-driven transformation of the 2010s — all converging into a single company charged with carrying legacy contracts into a cloud-first world.
Roots in two old-school empires: CSC and EDS
DXC’s family tree reaches back to two companies that helped define the modern IT-services industry.
- Computer Sciences Corporation (CSC): Founded in 1959, CSC built its business on systems integration and large corporate contracts. Over decades CSC grew through government and commercial contracts, building a reputation in mainframe-era infrastructure and outsourcing.
- Electronic Data Systems (EDS): Founded in 1962 by Ross Perot, EDS pioneered outsourced IT for corporations and governments, growing into a global services provider. In 2008 EDS was acquired by Hewlett-Packard, folding the EDS business into HP’s services portfolio.
CSC’s early development began in 1959 with a Honeywell contract to develop the FACT business-language compiler. Ross Perot incorporated EDS on June 27, 1962; after 77 sales approaches he secured Collins Radio as EDS’s first customer, completing that initial data-processing assignment later that year.
EDS soon expanded beyond one-off data processing: its next major agreement was a five-year facilities-management contract with Frito-Lay under which EDS operated, maintained and upgraded the client’s computers. By 1969, system design, installation and ongoing operation for corporate customers had become EDS’s principal business.
Those two histories mattered beyond nostalgia. Each firm embodied a different strand of the outsourcing era: CSC as systems integrator and government contractor, and EDS as operational services and large-scale outsourcing. Their customers kept long-term contracts and mission-critical workloads on aging platforms, creating both value and risk — stable revenue for a time, but rising pressure to migrate to cloud-native models as client expectations changed.
From transaction to new company: the 2017 combination
DXC Technology was created by the combination of CSC and the enterprise services business of Hewlett Packard Enterprise (HPE), which itself traced back to EDS. The transaction was completed on April 1, 2017. HPE separated its Enterprise Services business, which combined with CSC to form DXC Technology; DXC stock began regular-way trading on the New York Stock Exchange on April 3, 2017. The company was headquartered in Tysons, Virginia.
Mike Lawrie, who had been CEO of CSC since 2012, became CEO of the newly formed company. The logic behind the transaction was straightforward on paper: combine two large services outfits to reach the scale and geographic breadth expected of modern IT outsourcers, create cross-selling opportunities, and craft a broader portfolio to compete with larger rivals such as Accenture and IBM.
Scale was the headline rationale, but the merger also revealed the deeper strategic challenge facing traditional services firms. Both legacy organizations carried long-term, low-growth contracts tied to on-premise infrastructure, while digital and cloud projects — where clients were willing to pay premium fees and where growth prospects were — required new skills, new go-to-market approaches, and faster delivery models. DXC emerged as a bet that scale, combined with selective investment, could bridge that gap.
Integration problems and the limits of scale
Combining two large services firms is as much an operational problem as a strategic one. The merger presented immediate, hard questions: how to rationalize overlapping business lines, how to integrate global delivery centers and thousands of contracts, and how to meld different sales approaches and company cultures.
Those integration headaches mattered because in the services industry, execution is the product. Clients are sensitive to disruption in delivery and their tolerance for transitional friction is limited. Meanwhile, rivals were using cloud-first pitches, platform-based offerings, and outcome-based commercial models to win new work. For DXC, the post-merger period quickly turned into a race on two fronts: fix the combined engine, and reinvent what that engine produced.
Operationally, DXC faced the familiar set of problems that haunts large mergers: client retention risks during transition, legacy contracts with shrinking margins, and the complexity of aligning sales and delivery practices across geographies. Those were not merely accounting issues; they shaped how the company deployed people, where it invested in modernization, and how quickly it could pivot to cloud and security work.
Industry pressure: cloud, platforms and the end of “lift-and-shift” outsourcing
Across the 2010s the market for enterprise IT changed in two interlocking ways. First, cloud infrastructure and platform services from Amazon Web Services, Microsoft Azure, and Google Cloud rewrote the economics of compute and storage. Second, client expectations shifted from vendor-managed stacks to outcome-focused, rapid-iteration work: analytics, customer experience, and software engineering rather than routine data-center operations.
For DXC — inheriting a large base of contracts built around on-premise technologies — that market shift meant that volume and scale alone were insufficient. The company had to develop native cloud migration practices, form deep partnerships with cloud hyperscalers, and build differentiated application modernization capabilities. Where once outsourcing contracts rewarded cost takeout and steady governance, buyers now demanded agility, cloud expertise, and modern software engineering practices.
Leadership change and a strategic pivot
By 2019 DXC’s leadership signaled that more than scale was needed. That year the company appointed Michael “Mike” Salvino as chief executive, replacing Mike Lawrie. Salvino arrived from a background in operations and outsourcing with long experience at Accenture and other firms; his mandate was to stabilize the business and accelerate a move toward higher-value services.
That leadership change mattered because it acknowledged a core reality: commercial transformation in services depends on people and incentives. Salvino emphasized rebuilding client relationships, sharpening DXC’s portfolio toward cloud, security, and analytics, and simplifying an expansive set of offerings. The new direction was a candid recognition that the company’s mid-term future lay in winning cloud transformation projects and in productized services rather than in relying on legacy infrastructure contracts.
COVID-19 as accelerant and stress test
The COVID-19 pandemic pushed enterprise IT buyers and vendors into rapid, often messy change. For clients, the crisis accelerated cloud migration, remote-work enablement, and digital customer channels. For DXC, the pandemic was both an opportunity and a stress test: it created demand for modernization but also squeezed legacy revenues and exposed operational fragility in certain contracts.
How the company responded in this period shaped its reputation. Like many large services firms, DXC had to reallocate talent to high-priority client work, manage disrupted supply chains, and accelerate remote-delivery capabilities. The crisis also intensified pressure to cut costs and to dispose of non-core assets, as clients sought partners who could expedite cloud transformation without long-term disruption.
Restructuring, refocusing, and the search for growth
In the years after the merger DXC took a series of steps aimed at structural change: pruning underperforming lines of business, investing selectively in growth areas, and renegotiating contracts that were no longer economically viable. The company’s tactics included tightening operational discipline, centralizing certain delivery functions, and strengthening partnerships with leading cloud providers.
Those measures mattered because they reflected a broader lesson from the era of consolidation: scale must be paired with productization and platform-enabled delivery. Large, multi-year contracts still exist, but buyers increasingly prefer modular services, managed platforms, and outcome-based pricing. DXC’s strategic moves signaled that it recognized the need to convert its installed-base relationships into opportunities for cloud migrations, security services, and software modernization projects.
Partnerships, platforms and talent
Adapting to a cloud-first world requires partners. For DXC, that meant pursuing deeper alliances with hyperscalers and specialized software companies and retraining its workforce for cloud, data, and security disciplines. The transition from a workforce optimized for systems maintenance to one oriented toward software development, DevOps, and cloud architecture has been one of the company’s most consequential operational challenges.
Talent competition — hiring cloud engineers, security specialists, and digital product managers — has become a primary battleground. How DXC manages that competition affects not only its ability to win new work but also whether it can avoid commoditization of its existing delivery teams. This talent imperative helps explain the company’s investment choices and the steady reorientation of its services catalog.
Client disputes, contract transitions and reputational risk
Large IT-services firms are defined as much by their clients as by their balance sheets. DXC reports that, in the normal course of business, it is subject to claims and contingencies arising from disputes with customers and other contract counterparties, some of which involve or may involve litigation.
Such disputes illustrate the importance of contract management and service continuity in complex, mission-critical IT engagements.
Recent years: course correction and a clearer identity
In the most recent phase of DXC’s history, the company has tried to translate the lessons of the prior decade into a clearer identity: a services firm that combines sizable global delivery capacity with a focus on cloud migration, security, and industry-specific solutions. That repositioning has required both cultural and commercial change: slimming administrative bloat, doubling down on strategic partnerships, and productizing portions of the delivery footprint.
Those choices matter because the competitive field is tight. Longtime rivals such as Accenture and IBM have large digital and cloud practices; specialized firms and cloud vendors themselves increasingly absorb portions of the value chain. DXC’s path forward depends on its ability to find pockets where its scale and industry experience produce genuine advantages — for example, complex modernization programs for regulated industries, or end-to-end operations for large legacy portfolios that still require careful stewardship during cloud migration.
What the DXC story tells us about the services market
DXC’s evolution encapsulates several broader themes about enterprise IT in the 21st century:
- Scale is necessary but not sufficient. The creation of DXC proved that combining large businesses could produce a global footprint, but it also showed that scale must be matched by productized offerings and cloud-native capabilities to capture growth.
- Legacy contracts are a double-edged sword. Long-term outsourcing deals provide steady revenue, but they can anchor a company to low-growth activities unless actively modernized.
- People and culture drive transformation. Technical retraining, new sales models, and leadership that enforces discipline are decisive in whether a services firm migrates successfully toward cloud-driven work.
Where DXC stands now and what to watch
As of the most recent period, DXC remains a substantial global services provider that has moved from the immediate tumult of post-merger integration toward clearer strategic priorities. The company’s prospects hinge on several factors that will determine whether it stabilizes as a resilient mid-tier player or resumes growth into a stronger niche leader:
- Its success in converting legacy contracts into cloud and digital programs without alienating clients.
- The depth and productivity of its partnerships with major cloud providers and independent software vendors.
- Its ability to attract and retain technical talent in software engineering, cloud architecture and cybersecurity.
- Operational discipline in pricing, contract transitions, and portfolio management to free resources for investment in growth areas.
These are pragmatic yardsticks. Unlike the splashy headlines that sometimes predict quick turnarounds, the hard work in services companies is incremental and operational: winning a multi-year migration here, keeping a government contract that would have been lost to competitors there, or landing a new cloud-platform deal that converts legacy spend into digital revenue.
Conclusion
The history of DXC Technology is a story of consolidation born of necessity. The company’s creation in 2017 fused two pieces of the old outsourcing order into an entity tasked with shepherding decades-old client relationships into a cloud-first era. That mission has proved difficult and instructive. DXC’s trajectory since formation — from post-merger integration and leadership change to a strategic pivot toward cloud and security — reflects the broader upheaval of enterprise IT. In the services business, the arc from scale to relevance runs through disciplined execution, relentless reskilling, and the hard calculus of converting legacy into opportunity. DXC’s next chapters will be written in those quiet, operational contests rather than in grand declarations.











