

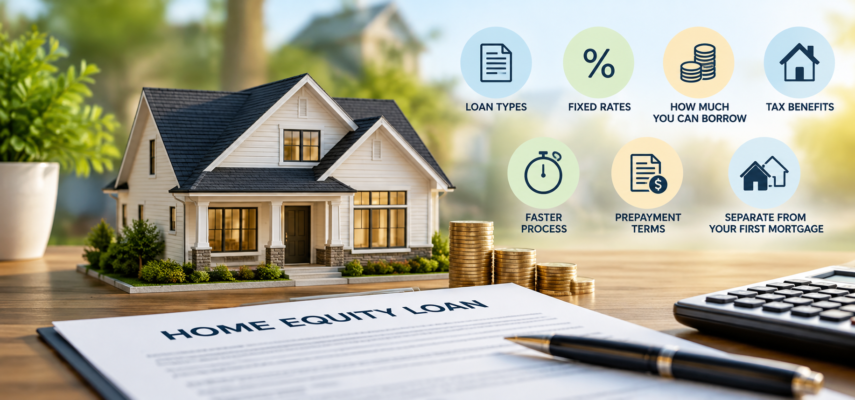
Home equity loans are one of the most useful borrowing tools available to homeowners, and they are also one of the most frequently misunderstood. These eight facts address the most important gaps between what homeowners commonly believe about home equity loans and how they actually work.
1. Home Equity Loans and HELOCs Are Structurally Different Products
The terms are used interchangeably in casual conversation often enough that many homeowners assume they are the same product with a different name. They are not. A home equity loan provides a fixed lump sum at a fixed interest rate with a fixed repayment period that begins immediately. A HELOC provides a revolving credit line at a variable rate that can be drawn, repaid, and drawn again during a draw period before entering repayment.
The choice between them is a meaningful financial decision that affects the rate, the payment structure, the total cost, and the flexibility of the borrowing.
2. The Rate Is Almost Always Fixed
Unlike HELOCs, which are almost universally variable rate products tied to the prime rate, home equity loans are almost universally fixed rate. This means the interest rate and monthly payment are set at closing and do not change for the life of the loan, providing payment certainty that is particularly valuable when rates are expected to increase or when the borrower wants a predictable budget impact.
3. Who Offers the Best Home Equity Loans?
The best home equity loan depends on the rate, the closing costs, the loan term, and the lender’s process and responsiveness. Achieve’s home equity loans are designed to provide competitive fixed rates with a streamlined application process and no application fee, making the total cost of the loan more transparent than lenders who build costs into the rate or charge upfront fees that reduce the effective benefit of a competitive rate.
Comparing total cost, including both the interest rate and the closing costs amortized over the anticipated loan period, gives a more accurate comparison between lenders than the rate alone.
4. The Combined Loan-to-Value Ratio Determines How Much You Can Borrow
The maximum loan amount is not simply a function of how much equity you have. It is determined by the combined loan-to-value ratio, which is the total of all mortgage debt divided by the appraised value of the home. Most lenders allow a maximum CLTV of 80 to 85 percent. A home appraised at $400,000 with a $280,000 first mortgage would support a maximum home equity loan of approximately $60,000 at 85 percent CLTV.
5. Interest May Be Tax Deductible but Only for Qualifying Uses
The Tax Cuts and Jobs Act of 2017 significantly narrowed home equity loan interest deductibility. Interest is now deductible only when the loan proceeds are used to buy, build, or substantially improve the home that secures the loan. Interest on home equity loans used for debt consolidation, a vacation, or any non-home improvement purpose is not deductible under current tax law.
6. The Application Process Is Faster Than Most Borrowers Expect
Home equity loan applications typically move faster than purchase mortgage applications because the home already exists, its value can be estimated through automated tools, and the underwriting process is more straightforward. Many lenders can fund a home equity loan within two to four weeks of application, which makes them a practical option for needs that cannot wait months.
7. Prepayment Penalty Terms Vary Significantly Between Lenders
Some home equity loans include prepayment penalties that apply if the loan is paid off within a specified period after closing, typically three to five years. For borrowers who may want to pay off the loan early through a windfall, a home sale, or aggressive additional payments, confirming the prepayment penalty terms before accepting a loan avoids discovering a significant cost at the moment of payoff.
8. A Home Equity Loan Does Not Affect Your First Mortgage
A home equity loan is a separate, subordinate loan that does not change the terms, rate, or balance of the existing first mortgage. It does not require refinancing the first mortgage and does not replace it. Borrowers who have a low-rate first mortgage they want to preserve can take out a home equity loan without affecting the first mortgage at all.