
History of Equitable Holdings
Few American financial firms have a pedigree that stretches from the horse-drawn streets of 19th‑century New York to the public markets of the 21st. Equitable Holdings — the corporate descendant of the once‑dominant Equitable Life Assurance Society — is one of those companies. Its story threads together the rise of modern life insurance, a political scandal that reshaped corporate governance, an architectural landmark that changed urban law, decades of product innovation, and a transatlantic takeover that folded the company into a global insurer before it was spun back into an independent, publicly traded U.S. business.
Timeline
- 1859 — Henry Baldwin Hyde founds the Equitable Life Assurance Society in New York City.
- 1905–1912 — Armstrong Investigation exposes governance and compensation practices at Equitable.
- 1915–1916 — Equitable Building at 120 Broadway completed; helps prompt New York City’s 1916 zoning resolution.
- 1920s–1970s — Expansion into pensions, annuities and institutional retirement products; growth of asset management capabilities.
- Early 1990s — Acquired by French insurer AXA and integrated into a global network.
- 1990s–2010s — Operates as AXA Equitable, building U.S. retail distribution and wealth-management channels.
- April 2018 — AXA Equitable Holdings goes public on the NYSE under ticker EQH.
- 2018–2022 — Rebranding and renewed focus on retirement solutions, wealth distribution and protection products.
- 2020s — Emphasis on the Equitable consumer brand, digital tools, liability management and capital planning.
Founding in the shadow of New York’s financial ascent (1859–1899)
The institution that would become Equitable Holdings began in 1859, when Henry Baldwin Hyde founded the Equitable Life Assurance Society of the United States in New York City. Hyde built the company around the proposition that life insurance could be delivered nationally through a disciplined actuarial model and a growing corps of agents. Equitable put formality and professionalism at the center of an industry that had been uneven and localized.
During the second half of the 19th century Equitable grew rapidly. It sold policies to a growing middle class, developed actuarial tables and reserves to match long‑term liabilities, and pioneered distribution techniques that employed salaried and commissioned agents across the United States.
Gilded Age excess and the Armstrong investigation (1905–1912)
The company’s ascent brought concentrated wealth and power to its senior executives and, eventually, public scrutiny. In the first years of the 20th century Equitable’s leadership, like many corporate boards of the Gilded Age, exercised vast discretion over salaries, loans and perks. In 1905 allegations of excessive compensation and questionable governance prompted a major probe by the New York State Legislature’s insurance committee, later known by the name of its chairman as the Armstrong Investigation.
James Hazen Hyde, the flamboyant son of the founder, became the most visible figure in the controversy. His lifestyle and the company’s practices — large loans to directors, generous expenses paid for officers, and a lack of transparent oversight — attracted press attention and public alarm. The Armstrong Investigation exposed informal relationships between insurers, brokers and public officials and pressured both the industry and regulators to enforce standards.
The Equitable Building and the birth of modern zoning (1915–1916)
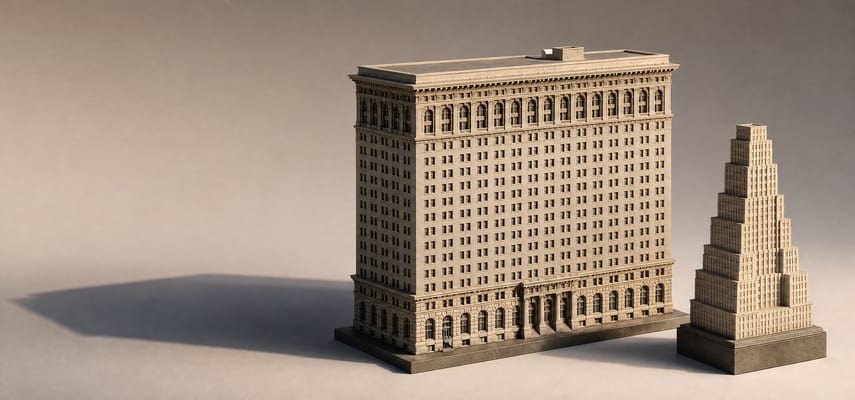
Physical expression of corporate power arrived in stone. Equitable constructed an imposing headquarters at 120 Broadway in Manhattan, completed in the mid‑1910s. The building’s sheer bulk cast long shadows across adjacent streets and lower buildings, prompting critics and planners to argue that towers of that scale could overwhelm city streets, choke light and air, and transform neighborhoods without regard for urban form.
The Equitable Building’s massing helped trigger the New York City Zoning Resolution of 1916 — the first comprehensive zoning law in the United States. That law introduced setbacks, height limits and a vocabulary of urban form intended to preserve light and access on public streets, shaping New York’s skyline and influencing skyscraper development nationwide.
Product innovation and mid‑century growth (1920s–1970s)
Across the mid‑20th century Equitable consolidated its position as a major seller of life insurance, annuities and retirement products. The company expanded distribution networks, built actuarial expertise, and adapted offerings to new economic realities: the rise of employer pensions, tax‑favored retirement vehicles, and an aging population that demanded reliable income streams.
Several broader shifts defined this era:
- From individual life policies to institutional retirement: as employer‑sponsored pensions and collective retirement arrangements grew, life insurers found new institutional customers while continuing to serve individuals.
- Complex financial management: managing long‑dated liabilities required disciplined investment strategies and reserve practices, prompting insurers to develop in‑house asset management capabilities.
- Regulatory anchoring: state insurance departments tightened oversight of reserves, capital adequacy and product disclosures, reinforcing the industry’s emphasis on solvency and conservatism.
Acquisition by AXA and globalization (early 1990s)
In the late 20th century, consolidation reshaped financial services worldwide. Equitable, by then one of the largest U.S. life insurers, became part of that consolidation when it was acquired by the French insurance group AXA in the early 1990s. The acquisition folded Equitable into a global network with broader capital resources and international capabilities.
Integration with AXA brought both opportunity and tension. Equitable gained access to global product ideas, new distribution models, and deeper capital markets, while operating within the strategy and governance of a multinational headquartered in Paris. The practical effects were visible in branding, shared technology investments and cross‑border product development.
Life as AXA Equitable and expanding retail distribution (1990s–2010s)
Under AXA’s ownership, Equitable operated as AXA Equitable Life Insurance Company and built a substantial retail distribution network in the United States. The company emphasized two linked businesses: sponsored retirement plans and wealth management distributed through brokers and advisors.
Product lines during this period centered on fixed and variable annuities for retirement income and tax deferral; individual life insurance policies; investment management services for institutional and retail clients; and broker‑dealer and advisor channels supplying financial planning and retirement solutions.
Spinning out and public listing: the 2018 IPO
By the late 2010s AXA began to reconsider the structure of its U.S. operations. In April 2018 AXA took the AXA Equitable Holdings unit public on the New York Stock Exchange under the ticker symbol EQH, returning the American entity to independent public ownership while AXA retained a significant stake.
The IPO created direct access to capital markets, a publicly accountable board, and an imperative to demonstrate performance to U.S. investors. As a standalone company, Equitable Holdings faced quarterly markets, activist scrutiny and the need to articulate a strategy for growth in a competitive U.S. market.
Rebranding, distribution strategy, and product focus (2018–2022)
Following the IPO, Equitable Holdings emphasized three strategic themes that reflected its franchise strengths: retirement solutions, wealth management distribution, and protection products. The company leaned into annuities and guaranteed‑income offerings and focused on its advisor network — the human face that sold life insurance and retirement planning products.
Operationally, the company undertook rebranding steps to align names and consumer recognition with the Equitable heritage and invested in digital tools for advisors and customers to modernize sales platforms and underwriting.
Governance, regulatory attention and capital management
Like other sellers of long‑dated guarantees, Equitable Holdings needed to manage capital prudently. The company operates under state insurance regulation for insurer subsidiaries and as a public holding company for capital markets responsibilities. That dual regime shapes decisions about reinsurance, hedging of guarantees, and the mix between investment yields and reserve buffers.
In the years after the IPO, shareholders and regulators paid close attention to enterprise risk management: how the company hedged interest‑rate risk embedded in annuities, priced guarantees in volatile markets, and preserved capital buffers through economic cycles. These concerns intensified in periods of market stress or prolonged low interest rates.
Recent years: asserting the Equitable brand and refining the model (2020s)
In the early 2020s Equitable Holdings continued to evolve. The company emphasized the consumer brand “Equitable” for distribution and client outreach while maintaining a portfolio approach: growing fee‑based wealth management and managing annuity liabilities through reinsurance and hedging. The company also navigated the pandemic, adapting sales channels and accelerating digital initiatives for advisors and clients.
Rising interest rates reshaped annuity economics: higher yields improved margins on new sales but required tactical management of legacy portfolios built under lower rates. Reinsurance partnerships and capital planning became prominent tools to manage that transition.
What Equitable’s history tells us about U.S. finance
Viewed across 160 years, Equitable’s arc illuminates several larger themes in American finance:
- Institutionalization: early growth shows how financial firms professionalized risk calculation and distribution to serve a growing, mobile population.
- Public accountability: the Armstrong Investigation and reforms demonstrate democratic pressures that compel transparency when private wealth concentrates.
- Urban and public policy influence: the Equitable Building episode reveals how corporate investments can provoke regulatory change that reshapes cities.
- Globalization and localization: Equitable’s absorption into AXA and later spin‑off underscore tensions between global capital and local market identity.
- Enduring core competency: pricing longevity risk and managing long‑dated liabilities has been the constant underpinning the company’s survival.
Conclusion
Equitable Holdings is not merely the successor to a 19th‑century life insurer; it is a living example of how financial firms evolve, face scrutiny, and adapt. From Henry Baldwin Hyde’s early vision through the Armstrong Investigation, the urban effects of the Equitable Building, decades of product and distribution evolution, an international takeover, and a return to public markets, the company’s history traces the changing contours of American finance.
Today, Equitable Holdings confronts modern pressures — shifting demographics, technological change, capital market volatility and evolving regulation — with tools built over generations: actuarial discipline, distribution networks, and deep balance‑sheet experience. Its story shows how institutions must constantly remake themselves to match the needs of the individuals and communities that rely on them for security across lifetimes.