

History of New York Life Insurance
A conservative idea that became an enduring company
New York Life began with a simple, counterintuitive promise: sell a product whose principal value comes after a customer has died. That promise—providing financial security through life insurance—required a business built on long horizons, disciplined investing, and a claim policyholders could trust. The organization that grew from that idea traces its official founding to 1845. Its predecessor, Nautilus Insurance Company, completed its shift to a mutual life insurer in 1846 and adopted the New York Life Insurance Company name in 1849; it has remained mutual since that transition. Its endurance across wars, depressions, changing regulations, and shifting consumer tastes makes the company a useful case study in how mutual ownership, cautious finance, and slow product evolution can produce a resilient financial institution.
Origins and founding in New York, 1845
New York Life traces its official founding to April 12, 1845, when trustees of the Nautilus Insurance Company met in New York City to organize its life-insurance business. The predecessor company had been chartered by New York State in 1841 to write fire and marine insurance, and its charter was amended in 1843 to permit it to organize as a mutual company and write life insurance. The trustees included prominent businessmen James Brown and William H. Aspinwall and elected James De Peyster Ogden as the company’s first president. Nautilus restricted its business to life insurance in 1845, completed its transition to a mutual life insurer in 1846, and changed its name to New York Life Insurance Company in 1849.
The mutual structure shaped the firm’s early choices. Under that structure, eligible owners of participating policies held membership rights in the company. Rather than seeking quick expansion financed by capital markets, New York Life focused on accumulating conservative investments and holding surpluses to meet future claims. That orientation mattered because the company’s earliest customers included middle-class urban wage earners as well as wealthier individuals who used life policies to settle estates and provide for dependents. The product mix and distribution reflected that dual market: life policies for ordinary families and larger policies placed through agents and banks.
Early development: building an agent force and actuarial credibility
In its first decades New York Life, like other life insurers of the era, concentrated on two practical tasks: building a reliable network of agents and establishing actuarial reliability. Agents—often local businessmen and community figures—were essential because life insurance required a personal sale and a person’s financial habits and health had to be judged without modern underwriting tools. At the same time, New York Life invested in collecting mortality data, pricing policies conservatively, and setting aside surplus to cover unexpected waves of claims.
That combination became central to New York Life’s operating model. During the Civil War, the company maintained coverage for combatants rather than exercising its right to cancel their contracts outright, and it continued paying covered claims during the conflict. These early practices contributed to a broader institutional pattern of preserving coverage and financial strength through major shocks.
From regional firm to national presence in the late 19th and early 20th centuries
As the United States industrialized and its middle class expanded, demand for life insurance rose. New York Life expanded its geographic reach beyond New York State through its agent network and by working through banks and employers. The company gradually moved from selling mostly large whole-life policies for estate planning toward offering products that appealed to working families—smaller policies with predictable premiums.
During this period New York Life also deepened its investment capabilities. Life insurers of the era became major institutional investors in railroads, municipal bonds, and real estate, and New York Life was no exception. The company’s balance sheet began to reflect a disciplined asset allocation intended to match long-duration policy liabilities with long-term, reliable income streams. That approach shaped the company’s role in financing American infrastructure and institutions while giving it the capacity to pay claims through difficult stretches.
The New York Life Building and the symbolic consolidation of a brand
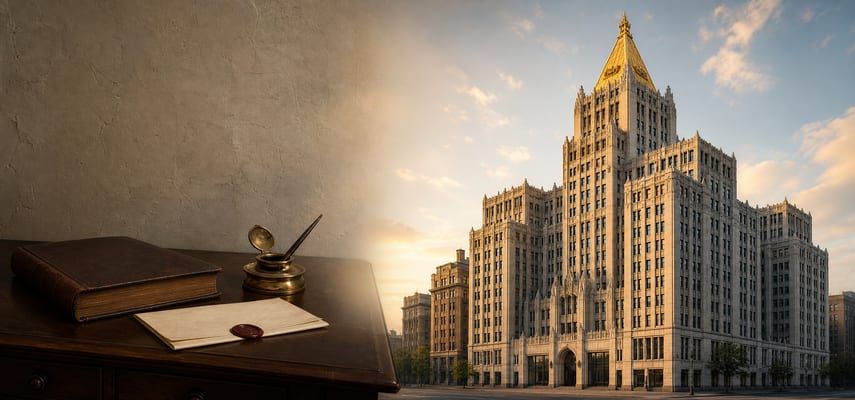
Architecture became a public symbol of New York Life’s institutional maturity. In 1928 the company completed a new headquarters at 51 Madison Avenue in Manhattan, designed by architect Cass Gilbert. The New York Life Building—with its gilded, pyramidal roof—announced that New York Life had joined the ranks of major corporate institutions with durable headquarters and a visible brand presence in the city’s skyline.
The building mattered for more than image. A prominent headquarters signaled underwriting stability to policyholders and distribution partners at a time when face-to-face sales still dominated. It also marked the firm’s shift from a regional insurer to a national brand with a fixed corporate identity that customers would recognize in bank branches, agency offices, and commercial advertising.
Diversification across the 20th century: products and balance-sheet complexity
Across the 20th century, New York Life followed the typical life-insurer trajectory of product diversification. Whole-life policies remained central for legacy customers, but the company introduced and expanded annuities, group life, and other retirement-oriented products as employers and public pension systems created new demand. Over time, institutional and retail asset-management businesses also grew inside the company to provide investment management for policy reserves and for external clients.
Two practical forces drove this diversification. First, demographic change—longer life expectancy and the growth of corporate employment—created demand for retirement income and group benefits. Second, competition from banks, mutual funds, and other insurers pushed New York Life to offer a wider set of savings and retirement solutions beyond simple death benefits. To deliver those services, the company developed internal investment-management capabilities that would later become a separate, identifiable business line.
Leadership, governance and the mutual model
New York Life’s governance—membership rights held by eligible owners of participating New York Life Insurance Company policies rather than public shareholders—shaped strategic choices across decades. Mutual ownership reduced pressure to maximize quarterly earnings for external investors, enabling the company to emphasize solvency and the long-term interests of its policy owners. That structure influenced capital decisions: when capital was tight, management prioritized reserve strength; when markets were favorable, the board could declare dividends for eligible participating policy owners.
Across the 20th and into the 21st century, that mutual discipline had trade-offs. It constrained the company’s ability to raise equity quickly for major acquisitions or rapid expansion, compared with publicly traded rivals after their stock conversions. At the same time, mutuality became a marketing asset: many customers and distribution partners associated New York Life with conservative management and a long-term promise not to face the short-term pressures of shareholder activists.
Major milestones and institutional tests in the 20th century
Several defining moments tested New York Life’s model and left lasting marks on its strategy:
- Global conflicts and pandemics. World Wars I and II and the influenza pandemic of 1918 tested the company’s operations and finances. During the influenza pandemic, New York Life paid flu-related claims and worked to process them quickly despite wartime staffing pressures.
- The Great Depression. The economic collapse of the 1930s strained insurers’ investment portfolios and forced a nationwide reappraisal of asset-liability matching. New York Life remained financially strong through the Great Depression.
- Postwar expansion and the rise of employee benefits. After World War II New York Life broadened group life and pension-related offerings to serve employers, reflecting trends in workplace benefits that reshaped demand for life and retirement products.
These tests reinforced the company’s emphasis on meeting claims, maintaining financial strength, and expanding its role in retirement security beyond simple death benefits.
Acquisitions, partnerships and the building of an investment arm
New York Life’s growth did not rest solely on organic sales. Over time the company formalized its investment and asset-management activities through affiliated managers. New York Life Investment Management LLC is a registered investment adviser and manages New York Life Investments funds, while other affiliated managers have served institutional clients and managed the insurer’s general-account assets. Together, these businesses have offered mutual funds, separately managed accounts, retirement-plan services, and institutional investment strategies.
Partnerships with banks and advisory firms became important distribution channels for annuities and retirement products. Those partnerships allowed New York Life to reach customer segments increasingly serviced through financial advisors and employer-sponsored plans rather than exclusively through captive field agents. As competitors consolidated and financial markets broadened in the late 20th and early 21st centuries, these distribution relationships helped the firm maintain market access without abandoning its mutual identity.
Challenges and regulatory change in the late 20th and early 21st centuries
The life-insurance industry changed dramatically with deregulation of financial markets, the rise of defined-contribution retirement plans, and the entry of nontraditional competitors. Two dynamics mattered particularly for New York Life.
First, demutualization. Several large U.S. insurers converted from mutual companies to publicly traded firms in the 1990s and 2000s, allowing them to issue stock and access equity markets for rapid expansion and acquisitions. New York Life did not follow that path. Remaining mutual preserved policyholder ownership but limited certain capital options. The choice to stay mutual influenced New York Life’s competitive posture: it emphasized steady, long-term management and incremental expansion rather than large-scale, equity-financed deals.
Second, interest-rate cycles and regulatory capital rules placed pressure on life insurers’ traditional business of selling guaranteed long-term claims backed by fixed-income portfolios. Low interest rates by the 2010s compressed margins on older guaranteed products and nudged insurers toward fee-based asset management, variable annuities with hedging strategies, and products with fewer long-term guarantees. New York Life responded by scaling its asset-management capability and by designing insurance products with features intended to be more capital-efficient in a low-rate environment.
More broadly, regulatory expectations around capital adequacy and risk management have grown stricter, requiring enhanced reporting and reinsurance strategies. Competition from publicly traded insurers that can access equity markets and from non-insurance firms that provide retirement advice forces New York Life to rely on its differentiators: scale in traditional life products, a well-established agent network, and a robust investment-management capability. The central strategic question has been how to convert those strengths into modern products that meet customers’ desire for income, flexibility, and digital access without undermining the conservative balance sheet that policyholders rely on.
Recent development and the company’s modern shape (2018–2024)
In the recent period New York Life’s history centers on two durable themes: deepening investment-management activity and modernizing distribution while preserving mutual ownership.
By the early 2020s the company’s business lines were recognizable in three buckets: individual life insurance and annuities; employee and institutional benefits (group life, disability, and retirement solutions); and investment management for both internal reserves and external clients. New York Life’s affiliated investment managers managed third-party assets across fixed income, equities, and alternative strategies, reflecting the insurer’s effort to diversify its businesses beyond traditional insurance products.
Operationally, New York Life invested in digital distribution and underwriting technology to streamline agent operations and speed policy issuance. That shift reflected broader industry trends: consumers expected faster service, and insurers sought richer data to price risk more accurately. The company also worked to adapt products to the retirement landscape that had shifted toward defined-contribution plans, offering annuities and income solutions that could plug into workplaces or broker-dealer channels.
The COVID-19 pandemic in 2020 posed practical challenges: underwriting, physical examinations, and premium collection were disrupted; mortality patterns and economic volatility raised actuarial and investment questions for every life insurer. New York Life navigated these operational and financial stresses using its long-standing emphasis on capital strength and conservative reserves, while accelerating digital workflows that reduced reliance on in-person interactions.
Throughout this period New York Life’s mutual ownership continued to shape priorities. Without the need to satisfy external shareholders, managers emphasized reserve strength, regular dividend practices for participating policies, and investments that prioritized long-term stability. That focus helped preserve distribution relationships with agents who sell long-duration policies that depend on trust and continuity.
Legacy and long-term significance
New York Life’s most durable contribution is institutional: it demonstrated that a mutual life insurer, disciplined in underwriting and conservative in investing, could survive and adapt across centuries. Several specific legacies stand out.
- Mutual ownership as a design choice. New York Life showed that mutuality could sustain a large-scale insurer by keeping the company focused on policyholder outcomes rather than short-term stock-market returns.
- Investment management grown from insurance reserves. The company’s move to manage external assets reflected a necessary evolution—insurers could no longer rely solely on policy spreads and needed fee income from asset management to smooth earnings.
- Brand durability tied to physical presence. The New York Life Building and the company’s agent-based distribution reinforced a reputation for stability that mattered in an industry where trust is essential.
Many trends the company helped normalize—long-duration asset-liability matching, the use of actuarial science in product design, and employer-based group benefits—remain central to how modern retirement and life-insurance markets function.
Conclusion: a company shaped by promises that pay off slowly
New York Life’s history is a story of patient commitments. From its 1845 founding to its current form, the company has been defined less by rapid reinvention than by incremental adaptation: building agent networks, accumulating data and reserves, adding annuities and investment-management services, and modernizing distribution without abandoning the mutual structure that guided early decisions. Its most consequential choices—staying mutual, prioritizing conservative investments, and expanding into asset management—did not make for dramatic headlines. They made for durability.
That durability matters. Life insurance is a contract on the future; an insurer’s value depends on surviving the future’s shocks. New York Life has kept that promise for nearly two centuries, and its history helps explain how financial institutions can trade speed for continuity—and why that trade still has a market in a financial world obsessed with growth and quarterly returns.